Group 1 Automotive UK losses double to £52m in 2025
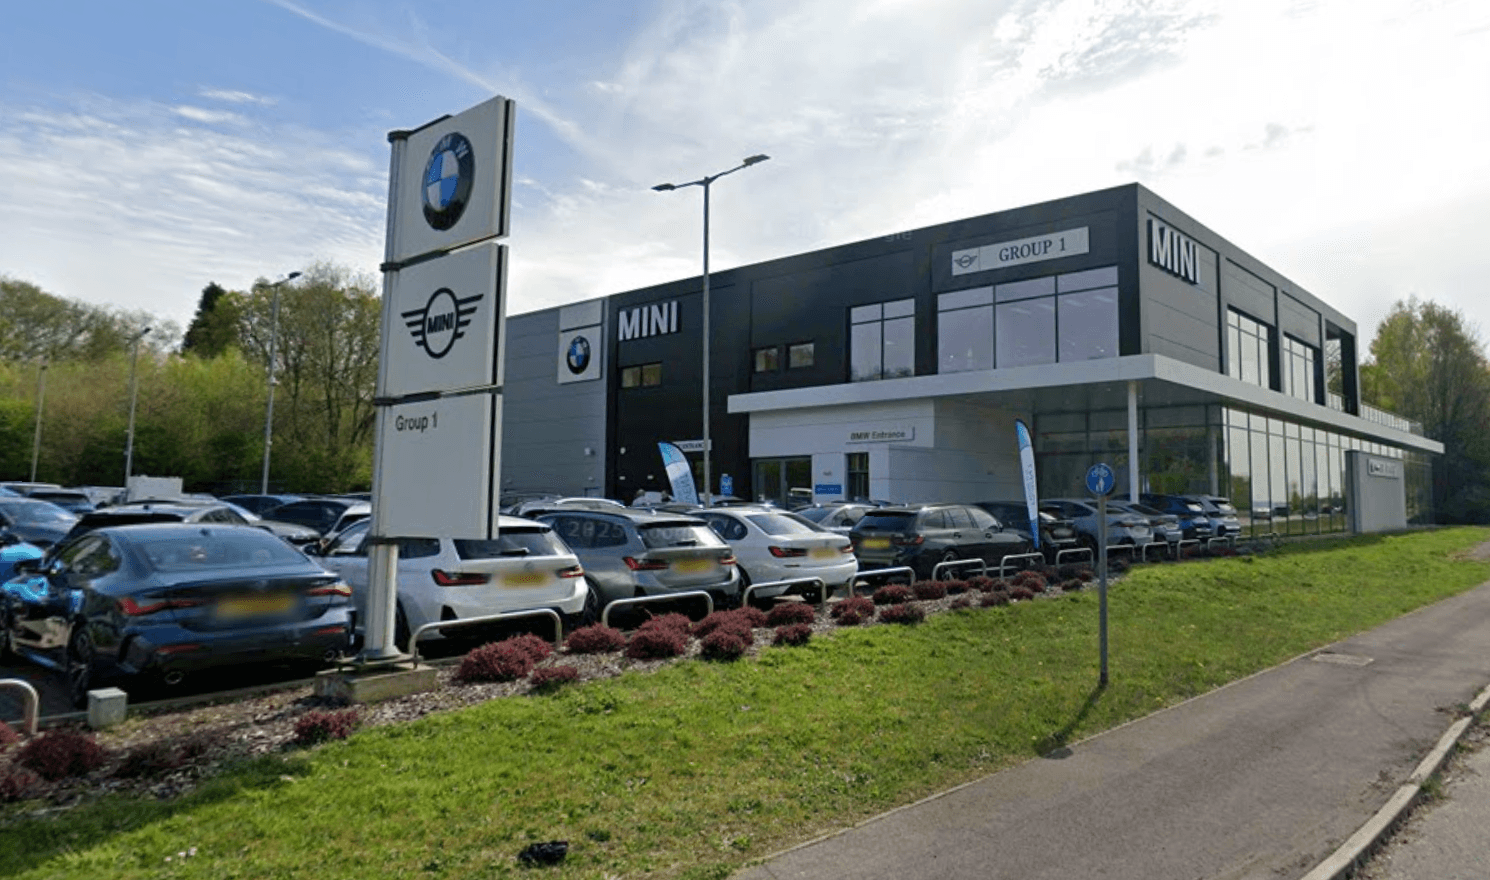
Group 1 Automotive's UK division posted a pre‑tax loss of £52.0m for the year to December 2025, double the previous year.
Group 1 Automotive's UK division reported a pre‑tax loss of £52.0m for the year to December 2025, double the £26.2m loss recorded in 2024. The loss occurred despite a 40% rise in revenue and higher new and used car volumes, highlighting the impact of restructuring costs on dealers.
Key takeaways
- Pre‑tax loss reached £52.0m in 2025, double 2024.
- Revenue grew to £4.51bn, up over 40% year‑on‑year.
- Restructuring and impairment costs totalled £33.9m.
- Dealer network fell from 114 to 109 sites after dropping JLR.
- New and used car volumes rose to 56,234 and 85,067 respectively.
Financial performance in 2025
The accounts show a pre‑tax loss of £52.03m for the 12 months to December 2025, compared with a £26.16m loss in 2024. Revenue increased to £4.51bn, a rise of more than 40% on the £3.23bn recorded the previous year.
Interest expenses grew from £35.5m in 2024 to £57.6m in 2025, contributing to the larger loss. When restructuring costs and impairments are excluded, underlying operating performance improved year‑on‑year, aided by the first full‑year contribution from recently acquired businesses.
Restructuring and network changes
Restructuring activity cost £16.5m, while impairment charges added another £17.4m to expenses. The group also announced the removal of Jaguar Land Rover from its brand portfolio, accelerating the reduction of its dealer network.
As a result, the number of sites fell from 114 to 109 across the UK. The network contraction reflects a strategic shift to focus on more profitable locations after the JLR exit.
Sales volumes and margin improvement
Despite the loss, the business shifted 56,234 new cars and 85,067 used cars to retail customers, up from 43,026 and 59,706 respectively in the prior year. Gross margins improved slightly, moving from 13.39% to 13.66%.
The rise in vehicle volumes helped drive the strong revenue growth, offsetting higher cost pressures but not enough to close the overall loss.
Staffing and cost profile
Employee numbers rose to an average of 7,032 in 2025, up from 5,246 in 2024, with technician headcount increasing from 1,512 to 1,628. Overall staff costs grew to £379.85m.
Director remuneration fell from £1.45m to £885,000, and the board did not recommend a dividend for the period.
What this means for dealers
The double‑digit loss underlines the importance of controlling non‑operational costs such as restructuring and interest charges. Dealers should scrutinise expense streams and seek efficiencies while maintaining sales momentum.
Higher vehicle volumes and improving margins show that growth opportunities remain, especially as integration benefits from recent acquisitions begin to materialise. Dealers that can leverage these trends may offset broader macro‑economic headwinds.
Frequently asked questions
Why did Group 1 Automotive's UK division post a larger loss despite higher revenue?
The larger loss was driven by a combination of higher interest costs, £16.5m spent on restructuring, and £17.4m in impairment charges. These non‑operational expenses outweighed the benefit of a 40% revenue increase and higher car sales, resulting in a bigger pre‑tax deficit.
How will the removal of JLR franchises affect UK dealers?
Dropping Jaguar Land Rover reduces the total dealer count from 114 to 109 sites, concentrating the network on remaining brands. Dealers may see a shift in product mix and need to re‑align marketing and inventory strategies to compensate for the lost JLR volume.
What should independent dealers watch for in the current UK market environment?
Dealers should monitor elevated interest rates, cost inflation and changing consumer demand, as highlighted by Group 1's director. Maintaining profitability will require tight cost control, efficient inventory management and a focus on high‑margin vehicle segments.
This article summarises reporting first published by Car Dealer Magazine.